
We interviewed Rebecca Bolton, a geoscientist specializing in geothermal risk management, about the unique characteristics and benefits of geothermal lithium. Three questions to help us learn and understand.
Could you explain, in simple words, what geothermal lithium is and how it is extracted from hot underground water?
A helpful way to picture it is getting two useful resources from the same underground water: heat and lithium.
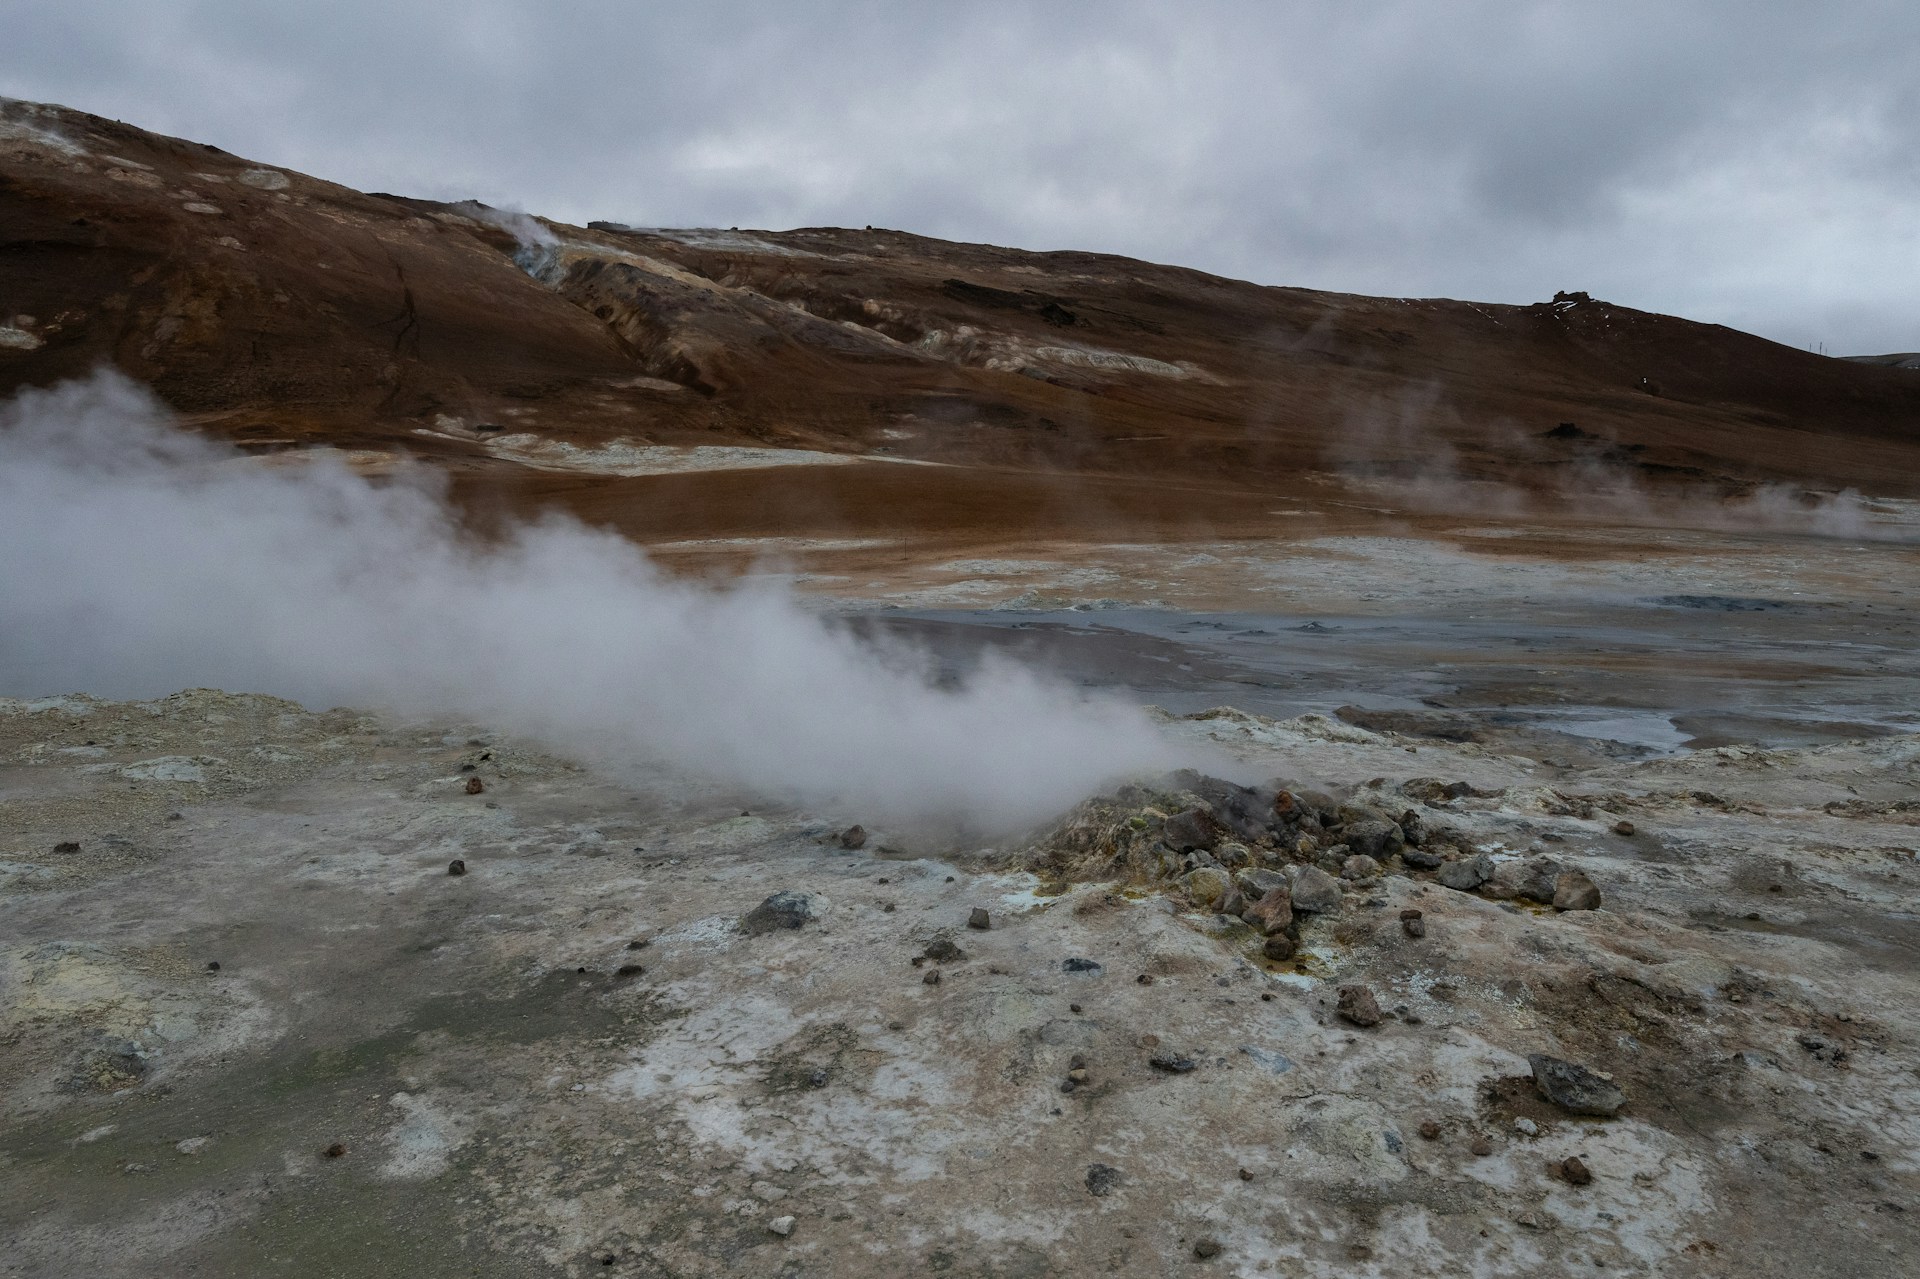
In some places, water deep underground is naturally hot and contains dissolved lithium, alongside other minerals. Wells bring this water to the surface, where its heat can be used for heating purposes or generating electricity.
The water also passes through equipment that captures the lithium. One approach uses a material that acts a little like a selective ‘sieve’, collecting lithium while leaving most other salts behind. The lithium is then recovered and purified, and the remaining geothermal water may be returned underground.
How does this method differ from conventional lithium mining, such as evaporation ponds in salt flats, and why is it presented as more environmentally friendly?
You may have seen pictures of the vast evaporation ponds used to produce lithium in salt flats in South America, known as salars. Salty water, or brine, is pumped into these ponds, where evaporation gradually concentrates the lithium before further processing. Another common approach is hard-rock mining, which involves excavating, crushing and processing lithium-bearing rock.
Geothermal lithium offers a different approach: recovering lithium directly from naturally hot underground water. It avoids large evaporation ponds and the excavation of large quantities of lithium-bearing rock. The surface facilities can occupy less land, the geothermal water is returned underground, and geothermal energy can help power the process and reduce carbon emissions. For a sense of scale, Vulcan’s Lionheart geothermal and lithium extraction site covers around 10 hectares, or 0.1 km², roughly 14 football pitches. Albemarle’s operation in Chile’s Salar de Atacama sits within a much larger lease area of around 137 km². It’s worth keeping in mind that these figures give us a sense of scale rather than a direct comparison: the salar area includes land beyond the ponds and equipment, while Lionheart’s wells and separate processing plant sit outside its 10-hectare site.
However, the starting concentration matters. Some salar brines contain lithium at concentrations of thousands of parts per million, whereas geothermal brines being considered for extraction often contain hundreds. Concentrations vary between sites, and the ranges can overlap, but lower concentrations mean processing more water to recover the same amount of lithium, assuming similar recovery rates. That is an important part of making a fair environmental comparison.
There is plenty of promise here, but the benefits need to be demonstrated for each project. Extraction and purification still require fresh water, energy and chemicals, and generate waste that needs managing. We therefore need to consider the full process and its impact for each tonne of lithium product produced.
I would describe geothermal lithium as a potentially lower-impact way of producing a mineral we need for batteries. Delivering that promise means carefully designing and operating each project, monitoring its effects, and involving local communities throughout.
What are the main uncertainties that still need to be resolved, and when could geothermal lithium be produced on a large scale, and in what quantities?
Lithium extraction is an exciting opportunity for some geothermal projects, but it won’t be possible everywhere. Geology determines where lithium occurs and how much is dissolved in the underground water. Even where it is present, commercial viability depends on its concentration, how much water the wells can sustainably supply, and the efficiency and cost of extraction. Where those conditions come together, producing lithium alongside heat or electricity can provide an additional source of income and strengthen the geothermal project’s business case.
As of November 2026, projects are at different stages. In Cornwall, GEL reports initial production at United Downs, with capacity for up to 100 tonnes of lithium carbonate a year (1). In Germany, Vulcan’s Lionheart project targets commercial production in the second half of 2028, with planned capacity of 24,000 tonnes of lithium hydroxide monohydrate a year (2).
In France, Lithium de France, is developing combined geothermal heat and lithium production in northern Alsace. Its published roadmap targets first lithium production in 2028, with the ambition of reaching 27,000 tonnes of lithium carbonate annually by 2031–2033, through a wider development programme (3).
Also in Alsace, the Ageli project, developed by Eramet and Électricité de Strasbourg, envisages 15,000 tonnes of lithium carbonate a year, with a final investment decision expected by 2030 (4). That is a decision about proceeding with the project, rather than a confirmed production start date.
These figures describe reported capacity or future targets, rather than amounts already produced over a full year.
There is plenty to be excited about. The next milestone is showing that these projects can deliver a dependable supply over time, supported by evidence from both the underground resource and day-to-day operations.

Rebecca Bolton
References